Market Review (September 2026)
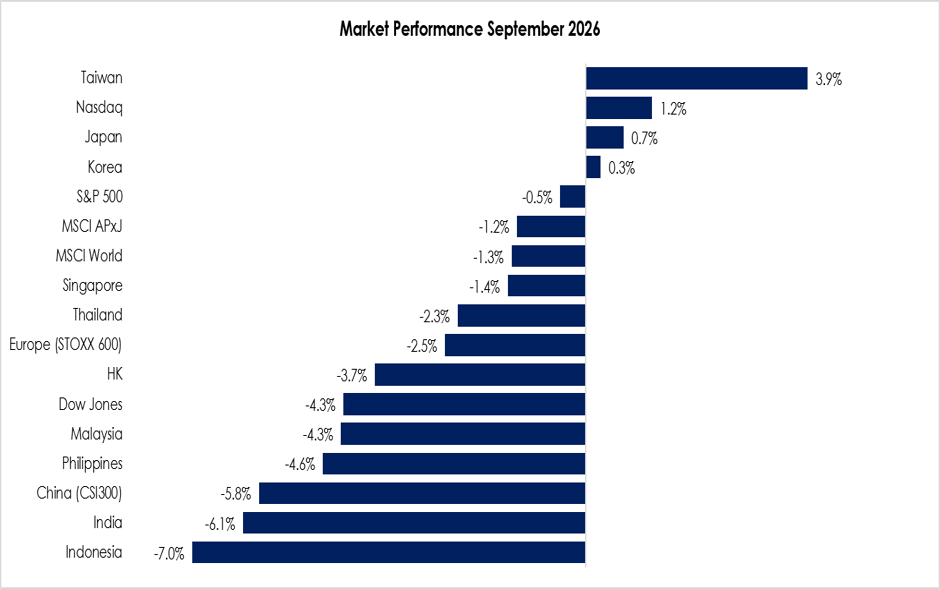
The MSCI Asia Pacific ex-Japan Index (-1.2%) marginally outperformed the MSCI World Index (-1.3%) in September, amid broad-based profit-taking and uneven regional sentiment. Taiwan (+3.9%) led the region, as continued investment in AI infrastructure and semiconductor demand supported technology-related stocks, while South Korea (+0.3%) remained resilient, extending its year-to-date gain to +62.3%. Taiwan also retained the strongest year-to-date performance at +65.5%. Conversely, Indonesia (-7.0%) was the largest monthly laggard and remained the weakest market year-to-date at -29.8%. India (-6.1%) and China (-5.8%) also declined sharply, followed by the Philippines (-4.6%), Malaysia (-4.3%) and Hong Kong (-3.7%). Thailand (-2.3%) and Singapore (-1.4%) recorded more moderate losses. Overall, September highlighted continued divergence between North Asian semiconductor beneficiaries and markets facing weaker domestic conditions, capital-flow pressures and external uncertainty. On the monetary policy front, regional central banks remained cautious as they balanced growth considerations against a firmer US dollar, elevated energy prices and evolving global monetary conditions. While inflation across much of the region remained manageable, policymakers continued to monitor the potential impact of higher oil prices and currency volatility on domestic price stability and economic growth.
Exhibit 1: Market Performance September 2026
Source: Bloomberg, PCM, 30 September 2026
The MSCI World Index (-1.3%) declined during the month, reflecting weaker sentiment across major developed markets amid a stronger US dollar, rising energy prices and renewed concerns over the global interest-rate outlook. Japan (+0.7%) was the only major developed market to register gains, supported by resilient corporate earnings and continued investor interest in technology-related exporters. In the United States, performance was mixed, with the Nasdaq (+1.2%) advancing on continued optimism surrounding artificial intelligence (AI) and semiconductor-related companies. However, the broader market remained under pressure, as the S&P 500 (-0.5%) and Dow Jones (-4.3%) declined amid concerns over higher energy prices, elevated bond yields and the prospect of interest rates remaining higher for longer. Meanwhile, Europe (-2.5%) also retreated as slowing economic momentum and persistent geopolitical uncertainties weighed on investor sentiment. Overall, developed market performance softened during September as investors reassessed growth expectations against a backdrop of firmer commodity prices and tighter financial conditions, although structural themes such as AI, digitalisation and semiconductor demand continued to support selected technology sectors.
The FBMKLCI Index declined by 4.3% month-on-month (m-o-m) in September, closing at 1,651.17 points. Meanwhile, the FBM Hijrah Shariah Index fell by 2.6%, while the Mid 70 Index and Small Cap Index declined by 2.6% and 1.0%, respectively. Sector-wise, the Energy sector was the best performer in September, rising 8.7% m-o-m, followed by Construction (+7.1%) and Utilities (+2.9%). Conversely, the Property sector was the worst performer, declining 7.5%, while Consumer and Finance fell by 6.5% and 5.1%, respectively.
Within the KLCI, the top three gainers in September were Gamuda Berhad (+14.9%), Telekom Malaysia Berhad (+3.8%) and YTL Power International Berhad (+2.8%). Meanwhile, the top three decliners were Sunway Berhad (-13.8%), RHB Bank Berhad (-13.6%) and IOI Properties Group Berhad (-14.6%). Foreign investors were net sellers, recording a net outflow of RM1.7 billion and bringing year-to-date (YTD) outflows to RM6.1 billion. Separately, seven companies were listed on the ACE Market in September: Evocom Berhad, GB Bond Holdings Berhad, SLGC Berhad, EcoSys (M) Berhad, EGH International Berhad, NEW Resources Group Berhad and RedPlanet Berhad.
For September, WTI crude oil advanced by 7.1% m-o-m to US$93.1 per barrel, while Brent crude oil surged by 9.5% m-o-m to US$101.8 per barrel. Crude palm oil (CPO) weakened to RM4,610/MT, declining by 5.8% from the previous month, while spot gold retreated by 6.5% to US$4,157.1/oz. On the currency front, the Malaysian ringgit strengthened by 1.3% m-o-m against the US dollar to RM4.0997/USD. Meanwhile, the US Dollar Index (DXY) rose by 2.1% to 101.5 points. Malaysia’s Consumer Price Index (CPI) increased by 1.9% year-on-year (y-o-y) in August 2026 (July: 1.8%), indicating that inflationary pressures remained broadly contained despite a slight uptick during the month. The increase in headline inflation was mainly driven by higher transport costs, housing and utility-related expenses, as well as firmer food prices, reflecting rising fuel costs and electricity-related charges.
Equity Market Outlook & Investment Strategy
MALAYSIA
Malaysia’s macroeconomic backdrop remained resilient in September, supported by healthy domestic demand, stable inflation and ongoing investment activity. Headline inflation edged higher to 1.9% year-on-year in August 2026 (July: 1.8%), although price pressures remained broadly manageable amid continued subsidy support and contained core inflation. Higher crude oil prices during the month, with Brent crude oil rising above US$100 per barrel, provided a supportive backdrop for the domestic oil and gas sector, while the plantation sector continued to benefit from relatively elevated crude palm oil prices despite a modest monthly correction. The services and manufacturing sectors remained key growth drivers, supported by sustained investment in digital infrastructure, data centres and artificial intelligence-related projects.
Separately, the FBM KLCI fell 4.3% in September amid weaker regional sentiment. Limited progress in de-escalating Middle East tensions, coupled with higher-for-longer US interest rates and elevated energy prices, reinforced inflationary concerns and supported a firmer US dollar. Beyond external headwinds, the prospect of an early GE16 raised political risk premiums, compounding foreign fund outflows. Nevertheless, Malaysia’s economic fundamentals remained supported by resilient domestic consumption, healthy investment momentum and continued progress in strategic infrastructure and industrial development initiatives.
REGIONAL / GLOBAL
Regional and global markets softened in September as a stronger US dollar, higher energy prices and uncertainty surrounding the global interest-rate outlook weighed on investor sentiment. The MSCI Asia Pacific ex-Japan Index declined 1.2%, marginally outperforming the MSCI World Index, which fell 1.3% during the month. Market performance across Asia was mixed, with gains concentrated in technology-oriented markets such as Taiwan, while most regional markets recorded negative returns. Continued optimism surrounding artificial intelligence (AI), semiconductor demand and digital infrastructure investment supported selected North Asian technology markets, although broader risk appetite remained subdued amid concerns over global growth and tighter financial conditions. Elsewhere, weaker performances in Indonesia, India, China and several ASEAN markets reflected cautious investor sentiment, foreign fund outflows and concerns over domestic growth momentum.
Against this backdrop, investment opportunities remain increasingly differentiated by earnings visibility, balance-sheet resilience and exposure to long-term structural growth themes. We continue to favour companies benefiting from sustained AI and digital infrastructure investment, including semiconductor supply chains, power infrastructure, grid modernisation and data-centre development. At the same time, a firmer US dollar, elevated crude oil prices, geopolitical uncertainty and the potential for monetary policy to remain restrictive for longer warrant a measured approach to portfolio construction. We therefore maintain a preference for high-quality businesses with durable cash flows, strong balance sheets and clear earnings visibility. A barbell strategy combining structural growth and income-generating assets, alongside broader geographical and sector diversification, remains well positioned to navigate near-term volatility while retaining exposure to long-term digitalisation and infrastructure investment trends.
Fixed Income Outlook & Strategy
MALAYSIA
Malaysian government bond yields are expected to remain broadly range-bound, supported by moderate consumer inflation, domestic institutional demand and expectations that BNM will maintain the OPR at 2.75% in the near term. Nevertheless, the sharp increase in producer prices warrants monitoring, as sustained energy and freight costs could gradually feed into consumer inflation and challenge the stable policy outlook. Elevated UST yields and the widening yield differential between US Treasuries and Malaysian bonds also pose risks to foreign demand, while Budget 2027 and the government’s financing outlook may influence longer-dated securities. Shorter maturities should remain relatively anchored by domestic policy expectations, whereas intermediate and longer tenors are likely to experience greater volatility. Higher prevailing yields offer opportunities to extend duration selectively, although a sustained rally would depend on easing global inflation pressures, stable foreign inflows and greater clarity over domestic fiscal requirements.
REGIONAL
US Treasuries weakened during September as persistent inflation, resilient economic activity and a more hawkish Federal Reserve prompted investors to reassess the monetary policy outlook. August nonfarm payrolls increased by 162,000, exceeding expectations, while unemployment remained at 4.1% and wage growth moderated to 3.1% year-on-year. Headline CPI rose by 0.4% month-on-month and 3.4% year-on-year, while core CPI increased by a stronger-than-expected 0.3% month-on-month, despite annual inflation easing to 2.4%. Producer inflation also accelerated to 5.4% year-on-year, reflecting renewed cost pressures. Against this backdrop, the Fed unanimously raised its policy rate by 25 basis points to 3.75%–4.00% on 16 September, its first increase since 2023, with median projections signalling another hike before year-end. Subsequently, September’s flash composite PMI rose to 58.4 from 56.0 in August, while initial jobless claims fell to 196,000 for the week ended 12 September, reinforcing evidence of economic resilience. Elevated oil prices, hawkish Fed commentary and weak demand at the five-year Treasury auction added to selling pressure, lifting the 10-year UST yield from 4.718% on 28 August to around 5.16%–5.29% in late September.
UST yields are expected to remain elevated and volatile; with an upward bias as firm economic activity and persistent inflation limit the scope for monetary easing. Although the September rate increase removed immediate policy uncertainty, the Fed’s projections leave open the possibility of further tightening, keeping shorter-to-intermediate maturities sensitive to inflation and employment data. Longer-dated Treasuries face additional pressure from substantial fiscal financing requirements and heavy issuance. Upcoming PCE inflation and labour market data will be important in determining whether expectations of further rate hikes are sustained. Meanwhile, developments in the Middle East remain a key source of uncertainty, as prolonged energy supply disruptions could reinforce inflationary pressures. Conversely, de-escalation and lower oil prices would support a recovery in bond prices. Overall, a sustained decline in yields would require clearer evidence of moderating inflation or softer economic momentum.
The Bank of Japan increased its short-term policy rate by 25 basis points to 1.25% in September, its highest level since April 1995, as persistent inflation and higher oil prices supported further monetary tightening. The 7–2 vote revealed differences over the pace of policy normalisation, although most policymakers favoured additional rate increases. Coming just three months after the previous hike, the decision signalled a faster pace of tightening, with inflation expected to remain above the BOJ’s 2% target and approach 3% by early next year.
Strategy for the month
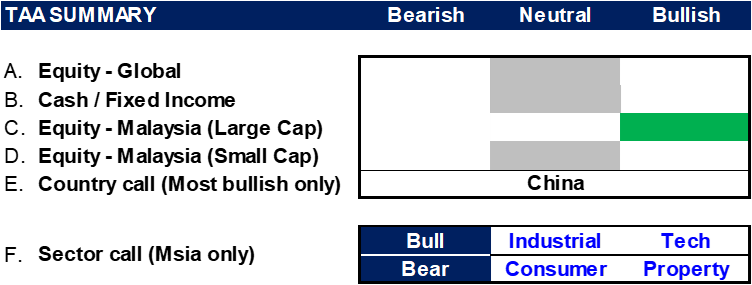
We maintain a neutral stance on global equities as U.S. markets trade near record highs, supported by resilient economic growth and strong corporate earnings. However, persistent inflation, elevated bond yields and potential policy uncertainty surrounding the upcoming U.S. midterm elections warrant a more selective approach. Geopolitical tensions and the outlook for global interest rates remain key risks to monitor. Within global equities, China remains our most preferred market, supported by attractive valuations, government policy measures and potential for a valuation recovery. We also favour selected U.S. companies with resilient earnings and strong fundamentals. Meanwhile, we maintain a neutral allocation to cash and fixed income to preserve portfolio flexibility.
In Malaysia, we maintain a bullish stance on large-cap equities, supported by resilient domestic fundamentals and earnings prospects, while adopting a neutral position on small-cap stocks, with emphasis on selective opportunities. Sector-wise, we favour Industrial and Technology. The industrial sector stands to benefit from infrastructure project rollouts, data centre investments and sustained capital expenditure, while technology offers opportunities from the semiconductor recovery and growing AI-related demand. Conversely, we remain cautious on the Consumer and Property sectors, as we see a less favourable near-term earnings outlook and persistent sector-specific challenges.
Exhibit 2: PCM’s monthly strategy snapshot
Source: PCM, 30 September 2026
Phillip Capital Malaysia and our offerings
We reaffirm our belief that there are still opportunities in the market, and we maintain a discerning approach in choosing high-quality stocks for our portfolio. However, it is crucial to exercise caution and carefully select investment options to ensure the best risk-adjusted returns. By taking a vigilant and discerning approach, investors can potentially reap the benefits of the current market opportunities while minimising risks.
A noteworthy avenue for investors seeking diversification in their portfolio is through PhillipCapital Malaysia. PhillipCapital Malaysia offers multiple private mandate services managed by professional fund managers. By leveraging PhillipCapital Malaysia’s private mandate services, investors can enhance their resiliency, optimise portfolio performance, and navigate the complexities of the market with confidence.
We also offer both conventional and Shariah-compliant options to cater to the needs of all investors. For Malaysia’s mandates, we like:
1. PMART/PMA Dividend Enhanced and/or PMART/PMA Dividend Enhanced ESG
Our PMART Dividend Enhanced and PMA Dividend Enhanced is an income-driven portfolio focused on high dividend-yielding equities. We apply the Dog of the Dow approach, screen and select top market cap stocks to minimise risk and ensure consistent performance. The portfolio is an equal weighting portfolio which reduces concentration risk and provides similar exposure to all clients, both initially and after rebalancing. We offer both conventional and Shariah investment options to cater to the diverse needs of our investors. Click here to learn more. We recently also introduced PMART/PMA Dividend Enhanced ESG Mandate as we remain dedicated to investing in ESG stocks given their stronger valuation and profitability.
2. PMART/PMA ESG
Phillip Capital Malaysia offers discretionary portfolio that invests in stocks with high ESG ratings from the F4GBM and F4GBMS Indices, namely PMART and PMA ESG. There are both conventional and Shariah options available. To explore the companies in which both Conventional and Shariah ESG mandates invest, you can refer to the provided link.
3. PMART/PMA Blue Chip and Opportunity
Our Blue-Chip portfolios primarily allocate our investments towards companies with large market capitalisations, while the Opportunity portfolios predominantly invest in companies with smaller market capitalisations. We also offer both conventional and Shariah-compliant options to cater to the needs of all investors.
Please click on the linkto learn more or email us at cse.my@phillipcapital.com.my if you require any further information.
Disclaimer
The information contained herein does not constitute an offer, invitation, or solicitation to invest in any product or service offered by Phillip Capital Management Sdn Bhd (“PCM”). No part of this document may be reproduced or circulated without prior written consent from PCM. This is not a unit trust or collective investment scheme and is not an obligation of, deposit in, or guaranteed by PCM. All investments carry risks, including the potential loss of principal.
Performance figures presented may reflect model portfolios and may differ from actual client accounts’ performance. Variations in individual clients’ portfolios against model portfolios and between one client’s portfolio to another can arise due to multiple factors, including (but not limited to) higher relative brokerage costs for smaller portfolios, timing of capital injections or withdrawals, timing of purchases and sales, and mandate change (e.g., Shariah vs. conventional). These differences may impact overall performance.
Past performance is not necessarily indicative of future returns. The value of investments may rise or fall, and returns are not guaranteed. PCM has not considered your investment objectives, financial situation, or particular needs. You are advised to consult a licensed financial adviser before making any investment decisions.
While all reasonable care has been taken to ensure the accuracy and completeness of the information contained herein, no representation or warranty is made, and no liability is accepted for any loss arising directly or indirectly from reliance on this material. This publication has not been reviewed by the Securities Commission Malaysia.